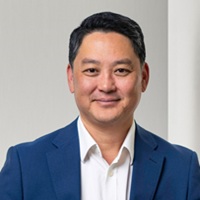
James Nguyen (Bell Asset Management) explores the misconceptions and opportunities in Australian small caps, including what the risk of recession means for this sector
Australian small caps are publicly listed companies on the Australian Securities Exchange (ASX) that sit outside the top 100 largest companies by market capitalisation. This sector offers a mix of high growth potential and diversification that active investors can exploit.
In the 23 years James Nguyen — Portfolio Manager of the Bell Australian Small Companies Strategy at Bell Asset Management — has been investing in Australian equities, he believes there has never been a more compelling time to invest in Australian small caps.
In making the case for Australian small caps, James says all the ingredients are there for small caps to outperform. He cites industry data which shows there are four key areas that support small caps:
- Absolute valuation — Small caps are cheap to buy and are currently trading on about 15.5x forward earnings. Small caps are also trading on about a 10 per cent discount to where they have historically traded.
- Relative valuation — Small caps are cheaper than most growth asset classes. Historically, small caps have traded at a premium of about 15 per cent to large caps, which is reflective of their superior earnings growth. Currently, small caps are trading at about a 10-15 per cent discount to large caps.
- Dividend yield — For the first time since the GFC, small caps are offering a higher dividend yield. Small cap companies are generating strong cashflow and returning that back to shareholders.
- Earnings growth — Rising revenue, expanding profit margins, and growing earnings per share is helping to drive share prices of small caps higher compared to large caps. Small caps are expected to deliver 26 per cent earnings growth over the next 12 months versus 7 per cent for large caps.

James Nguyen
Portfolio Manager
Bell Asset Management
By Jayson Forrest
Over the last 10 years, the composition of the small caps index has significantly changed. Ten years ago, the ‘materials’ sector in small caps was 19.2 per cent of the S&P/ASX Small Ords Index, whereas today, it’s 28.4 per cent. Driving that growth is gold — a defensive asset — with the composition of gold in the index exceeding 13 per cent
An opportunity or value trap?
Speaking at a session titled ‘Under the radar: The hidden champions of the Australian market’ at the 2026 IMAP Independent Thought Conference, James credits higher interest rates and common misconceptions as reasons for why the small caps sector is currently so attractive for investors.
“Traditionally, the market has responded to higher interest rates by selling off small caps,” says James. “That’s because higher interest rates increase the probability of central banks pushing economies into recession. Small caps are perceived to be highly cyclical, both from an operational and a financial leverage perspective, which can lead to the sell-off of this asset class.”
He says investors continue to view small caps as nascent in their business models, with little sustainable competitive advantage (that allows a company to protect its long-term profits and market share from competing businesses) and generally, without product diversification. This means in times of stress, small caps have limited ability to tap into equity and debt markets.
“Therefore, if you think the central bank will push the market into recession, you would traditionally sell-off your small caps. That’s because small caps can underperform in this type of environment.”
However, despite U.S. 10-year Treasuries tracking at 5 per cent — and over the last 25 years, U.S. 10-year Treasuries have only reached this level twice, and in both times, the U.S. economy went into recession — James doesn’t believe either the Australian or U.S. economies are poised to tip into recession.
When you compare the defensive sectors in small caps at almost 30 per cent and large caps at about 15 per cent, I believe small caps can still outperform, even if we do go into a recession, which I don’t believe we will
Resilience in a recession
The investment team at SPC, working with JPAAM, was able to close the gap between retail and institutional by rebuilding the managed account mechanism itself. With the help of JPAAM, two purpose-built Australian unit trusts now sit inside SPC’s retail MDA structure, which directly provides the investment committee with institutional-grade implementation capability.
The Findex MDA trusts (managed by JPMAM) comprise of the Equity Trust (45 per cent Australian/55 per cent global, a multi-factor core, with the ability to put index futures and options over the top of that) and Fixed Income Trust (50 per cent Australian/50 per cent global, a research-enhanced core, with the ability to put bond futures and FX forwards over the top of the core).
As a result of this rebuild, reallocations that once took weeks, now reach every client account within 48 hours, and at a fraction of the previous cost. Kieran adds because implementation sits at the trust level, the investment committee can express a precise tactical view — whether a duration call, a sector tilt, or a currency hedge — without disturbing the manager panel or the client’s day-to-day portfolio.
Essentially, this framework means that tactical investment decisions are executed centrally at an overarching trust level, keeping the underlying roster of fund managers completely insulated from disruptive adjustments.
Tools like FX hedging and derivative overlays, which were once out of reach for retail managed accounts, are now standard tools in how SPC implements tactical views for advisers and their clients.
However, Kieran stresses that a rebuild like this requires scale and strong investment governance. “This type of solution requires more than A$1 billion in the fund structure to get the pricing right, as well as a high-quality investment committee that can make and execute decisions fast,” says Kieran.
All the preconditions are there for small caps to outperform. There is superior earnings growth, superior dividend yield, and your starting point from a multiple perspective is so much cheaper than other growth asset classes
Artificial intelligence: Think outside the box
Artificial intelligence (AI) is arguably the hot topic of the day and a sector that presents investors with many opportunities. James believes when investing in small caps, investors need to look beyond the obvious, which often means “thinking outside the box”.
According to James, there are many “hidden AI winners” and a lot of them are in the small caps market. He identifies six hidden AI themes and small cap opportunities:
1. Electrification transformation requires copper and aluminium — for copper, think Capstone Copper, Austral Resources, Aeris Resources, Firefly Metals, and Glencore; and for aluminium, think Alcoa.
2. Electrification needs battery and battery storage. This requires lithium — think Elevra Lithium, Patriot Metals, Wildcat Resources, and Vulcan Energy.
3. Electrification needs industrial magnets. This requires rare earths — think Viridis Mining, St George Mining, Iluka Resources, Arafura Rare Earths, and Lindian Resources.
4. Data centres need reliable cheap power. This requires uranium — think NexGen, Bannerman, Deep Yellow, and Lotus Resources.
5. Data centres need to be built and integrated into the grid. This requires contractors — think Genus Plus, Southern Cross Electrical, Tasmea, Maas Group, Symal, IPD Group, and Mayfield Group.
6. Data centres and chips/servers require recycling — think Sims Group.
“If you look outside the box, you can find these types of fantastic businesses that are trading at very low multiples and have exposure to specific themes,” says James. “And when the market finally latches onto these companies, the market drives the share price re-rate.
“Subsequently, an investor’s returns can be a ‘multibagger’ (where an equity investment yields returns exceeding 100 per cent of its initial cost, effectively multiplying the original investment multiple times over — such as a two-bagger for a 200 per cent return or a 10-bagger for a 1,000 per cent return).”
Think outside the square. Avoid investing in the most obvious companies and instead, think about the second and third order of beneficiaries of the thematics you want exposure to. That’s the way an investor can make money
A compelling asset class
When considering Australian small caps as part of any portfolio allocation, James believes investors should remember three key points that make this asset class so compelling:
- There is an outstanding opportunity for investors in small caps. “All the preconditions are there for small caps to outperform. There is superior earnings growth, superior dividend yield, and your starting point from a multiple perspective is so much cheaper than other growth asset classes.”
- There are misconceptions around the risk within small caps. “The composition of the small caps benchmark has changed over time, however, people’s perception of that benchmark hasn’t. And that’s where the opportunity lies with small caps, because it has traditionally sold off on that risky perception.”
- Small caps offer a multitude of ways to play AI and other thematics. “Think outside the square. Avoid investing in the most obvious companies and instead, think about the second and third order of beneficiaries of the thematics you want exposure to,” says James. “That’s the way an investor can make money.”
About
James Nguyen is Portfolio Manager of the Bell Australian Small Companies Strategy at Bell Asset Management.
He spoke on the topic ‘Under the radar: The hidden champions of the Australian market’ at the 2026 IMAP Independent Thought Conference.